A manager’s willingness to disclose is a strategic choice. The same secrecy can protect a valuable investment process or shelter a weak one. Economic theory explains why those motives can coexist. Recent empirical research shows why inconsistencies in risk disclosure deserve separate scrutiny. For allocators, the distinction turns on what is withheld, what remains verifiable and how quickly the available evidence allows different explanations of performance to be separated.
1. When silence carries more than one meaning
An attractive track record does not settle what limited disclosure means. An asset manager may be protecting a process that competitors could copy. A manager without a durable edge could offer the same explanation. Strong reported returns can make either account appear credible, while leaving the underlying difference unresolved.
The ambiguity lies in the relationship between performance and disclosure. A selective investor base, a confident presentation or a claim of proprietary methods adds to the narrative, but does not necessarily distinguish its competing explanations. What matters is whether the information available over time makes those explanations easier to separate.
2. Two routes to demonstrating ability
Investors can learn about managerial skill from both performance and transparency. Disclosure speeds learning but costs money and can leak valuable strategies. Highly skilled managers may therefore rely on results over time. Low-skilled managers choose opacity too, benefiting from being initially grouped with stronger managers. Intermediate managers can instead disclose to distinguish themselves from weak ones.[1]
This is countersignalling: the strongest type need not use the signal chosen by an intermediate type. It is a conditional theoretical result, not a ranking rule for actual funds. Transparency does not establish mediocrity; secrecy does not establish talent. The model explains why a disclosure choice alone need not identify ability.[1]
3. The information game and its limits
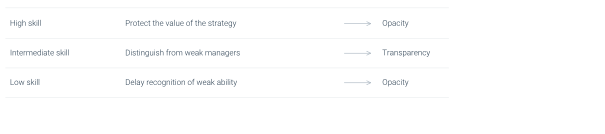
Based on Gervais and Strobl (2020).[1] Conceptual illustration of the model’s countersignalling equilibrium; these are theoretical types, not observed classifications of funds.
The mechanism depends on costly transparency and informative performance. Its relevance weakens when neither route lets investors learn much. A long record may still leave an allocator unable to disentangle skill from leverage, market exposure or valuation choices. That is a reason to specify the evidence needed to assess the manager, rather than treating the passage of time as verification.
A useful distinction is between confidentiality about how returns are generated and accountability for how capital is managed. In our application of the theory, a manager can protect trade construction while still offering a credible way to verify exposures, valuation procedures and conflicts. The appropriate information arrangement will depend on the strategy and mandate.
4. Recent evidence on selective disclosure
Approximately 40% of hedge-fund adviser disclosures in a 2014–2018 sample contained inconsistencies concerning operational or investment risks when compared with other public information. Inconsistent funds subsequently performed worse, without corresponding differences in fund flows. The study concerns SEC-registered advisers matched to the Lipper TASS hedge-fund database, which supplies fund returns and characteristics; it is not a current census of the industry.[2]
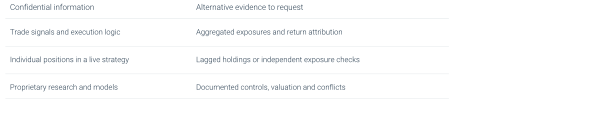
Y-CG analytical framework. Illustrative verification requests, not regulatory requirements or findings estimated in the cited studies. Access and independence should be established for the specific mandate.
5. The value of making differences observable
The two studies concern different information choices. The model explains how secrecy can coexist with skill; the empirical study examines inconsistencies in risk disclosures. Together they suggest a distinction between information that protects the production of returns and information that helps investors interpret those returns. Their implications meet at the question of what remains observable, even when some details remain private.[1,2]
The practical implication is that the value of disclosure depends on the uncertainty it resolves. A detailed account of an investment philosophy may leave the sources of returns difficult to assess. More limited information about exposures, valuation or conflicts may do more to separate competing explanations of performance. The volume of communication and its usefulness for evaluation need not move together.
Opacity also has a time dimension. Its significance depends on whether subsequent evidence can reveal differences that are initially hidden. Where independent verification remains possible, confidentiality can coexist with meaningful evaluation. Where the explanation for secrecy also prevents that evaluation, ambiguity can persist. The analytical focus therefore shifts from how much a manager reveals to how the information arrangement affects learning about the manager.
References
[1] Gervais, S., & Strobl, G. (2020). Transparency and talent allocation in money management. The Review of Financial Studies, 33(8), 3889–3924.
[2] Liu, Y., Madsen, J., & Zhou, F. S. (2026). Strategic (inconsistent) disclosures and sophisticated investors: Evidence from hedge funds. Journal of Accounting Research, 64(2), 923–978. First published online September 2, 2025.
Important notices
This document has been prepared by Y-CG (“Y-CG Research”) for informational purposes only and is intended exclusively for institutional and professional recipients. It does not constitute, and should not be construed as, investment advice, a recommendation, an offer to sell, or a solicitation of an offer to buy any security, financial instrument, or service, or participation in any trading strategy.
The information contained herein has been obtained from or is based upon sources believed to be reliable, but Y-CG makes no representation or warranty, express or implied, as to its accuracy, completeness, or fitness for any particular purpose. All information, views, and estimates are subject to change without notice. References to research findings, models, indicators, or historical relationships are provided for illustration only; they are not a guarantee of future results, and no representation is made that any objective, projection, or signal will be achieved. Forward-looking analysis is inherently uncertain.
Nothing in this document creates a fiduciary, advisory, or contractual relationship between Y-CG and any recipient. Recipients should make their own independent evaluation of the matters described herein and, where appropriate, seek advice from their own professional advisers. Y-CG is not a registered investment adviser, broker-dealer, or credit rating agency, and nothing herein constitutes regulated investment research, a credit rating, or legal, accounting, or tax advice.
Third-party findings are attributed in the relevant source notes. No endorsement by the cited authors or publishers is implied.
The distribution of this document may be restricted by law or regulation in certain jurisdictions. This document may not be reproduced, redistributed, or disclosed, in whole or in part, without the prior written consent of Y-CG. © 2026 Y-CG. All rights reserved.
Contact: connect@y-cg.com; www.y-cg.com